6 min read 22 Nov 2026
Appointment and qualification of directors explained simply
CA MONK Team
Article Topics
A company is run by a small group of people called its directors, who together form its board. Company law has rules on the appointment and qualification of directors: how many a company needs, who may be one, how they get the job and what paperwork follows.
Think of them as the hiring rules for the top table, so that a company is never steered by someone the law has barred.
Riya and Kabir Shah are siblings who set up Golden Crust Bakeries Private Limited in Pune to run three bakeries. A private company needs at least two directors, so the pair is exactly enough. A public company needs at least three, and a one-person company needs one. Fifteen is the normal ceiling; going above it needs a special vote of the shareholders.
Their company's rulebook names no directors. In that case, the individuals who signed the company's founding documents are treated as its first directors until others are properly appointed. So Riya and Kabir are the first board.
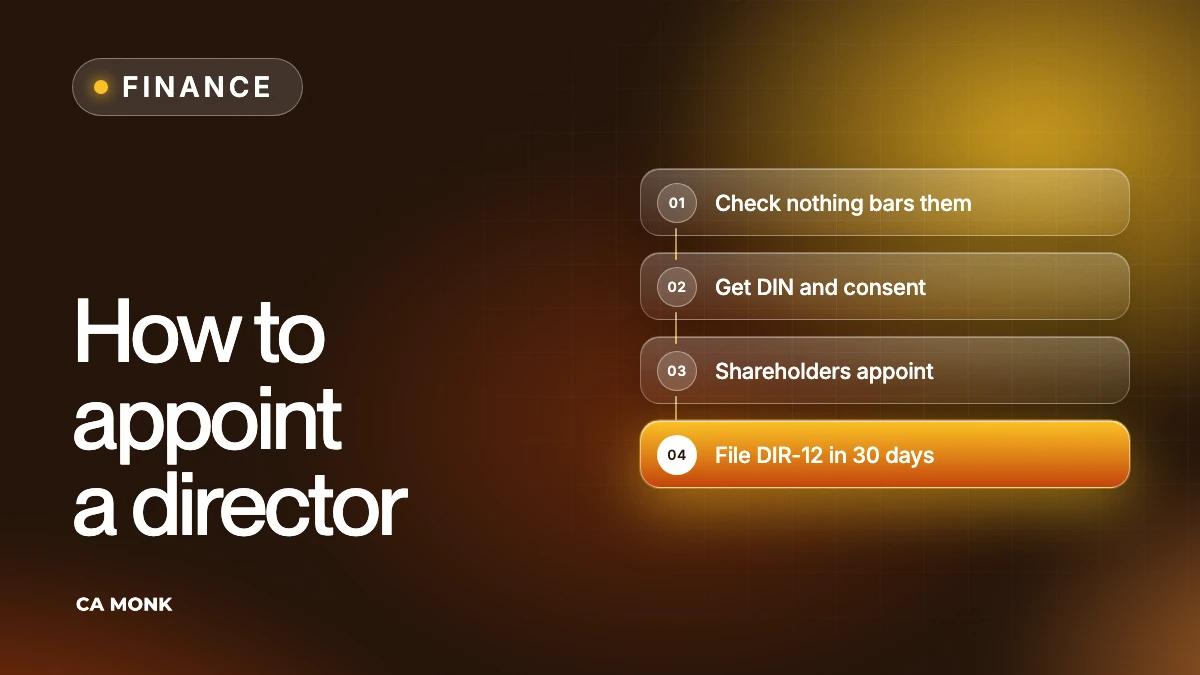
Every director needs a personal number issued for directors (Director Identification Number, or DIN). It must be quoted in the papers for the appointment. The person must also agree in writing to serve, and that consent goes to the government's Registrar of Companies within 30 days.
Normally, directors are appointed by the shareholders at a general meeting. The company then tells the Registrar about every new director on a set online form (Form DIR-12), also within 30 days. It also updates its own register of directors.
One rule catches founders who move abroad. Every company needs at least one director who spent a total of at least 182 days in India in the previous calendar year. In 2026, Kabir moves to Dubai to look after export orders and spends only 100 days in India. Riya stays in Pune all year, about 365 days. Riya has more than 182 days, so Golden Crust is fine. If Riya had moved too, the company would have needed to find a director who did stay in India for 182 days.
While Kabir is away, the company can appoint someone to act in his place for any absence from India of at least three months (alternate director).
The bakeries grow, and in August 2026 the siblings want Mr. Desai, a retired finance manager, on the board straight away. Their next annual meeting of shareholders is not until September. If the company's rulebook allows it, the board can appoint him itself, without waiting (additional director). The catch is that his term ends at the next annual meeting, or the last date by which it should have been held, whichever comes first. To keep him, the shareholders must appoint him at that meeting.
Before the board appoints him, the company checks whether he is allowed to serve. A person cannot be appointed if, among other things:
The last one needs a date check. Mr. Desai owed ₹50,000 on shares in another company, due on 1 January 2026. He paid it on 15 March. That is well inside six months, so he is not barred. If it had still been unpaid on 1 July, six months after the due date, he would have been.
The company also counts his other board seats. A person can be a director of at most 20 companies, of which no more than 10 may be public companies. Mr. Desai already sits on 18 boards, 9 of them public. Golden Crust is private, so adding it takes him to 19 in total, still within 20, and leaves his public count at 9. He can take the seat.
The board appoints him on 10 August. Counting 30 days from then, the Form DIR-12 must reach the Registrar by 9 September.
Golden Crust also takes a bank loan to open a fourth outlet. The loan agreement gives the bank the right to put its own person on the board, to watch over its money (nominee director). Investors and the Government sometimes hold the same right.
Public companies have one more rule. At least two-thirds of their directors must be ones whose term ends in turn, a few at a time (retirement by rotation). At each annual meeting, one-third of those directors retire, starting with those who have served longest. Say a public company has 9 directors. Two-thirds of 9 is 6, so at least 6 must rotate. One-third of 6 is 2, so 2 of them retire at each annual meeting.
The most common slip is treating an appointment as done without checking two things: that the new director's DIN is active, and that nothing bars the person from serving. The second is missing the 30-day deadline for Form DIR-12, or forgetting to update the company's own register of directors.
Not if neither spends enough time in India. At least one director must have been in India for 182 days or more in the previous calendar year. If both founders spent 150 days each, the company needs another director who meets the 182-day rule.
Only until the next annual meeting of shareholders, or the last date it should have been held, whichever is earlier. Someone appointed in June stays only until the September meeting unless the shareholders then appoint them.
Yes. Twenty in total, of which no more than ten can be public companies. A person already on 20 boards must give one up before joining another.
This post was checked against the law in November 2026. Laws change, so read the official text before you act on it.
These related guides explain other parts of how companies are run under the Companies Act.

CA MONK Team
CA Career & Learning Platform
CA MONK Team is the team behind CA Monk, India's CA career and learning platform. We help Chartered Accountants and CA aspirants build skills, explore career opportunities, connect with mentors, and navigate their professional journey through courses, mentorship, career tools, placements, and practical industry insights.
